EV Batteries in China: Chemistry, Scale, and Supply Chains - ChoZan
Alt text:BYD’s Blade Battery Factory in ChongqingChina’s dominance in EV battery production is no longer a forecast. It is a fact of global industrial life. In 2025, Chinese manufacturers controlled around 70. . .
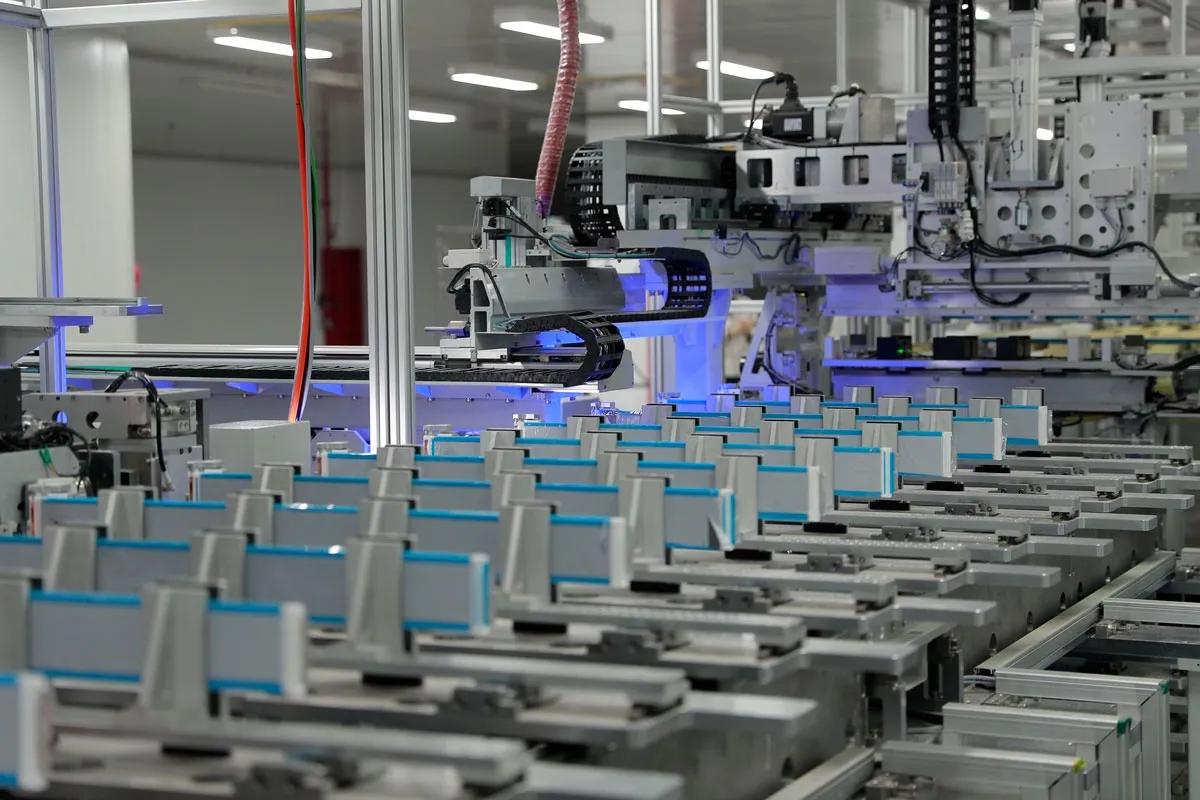
Alt text:BYD’s Blade Battery Factory in ChongqingChina’s dominance in EV battery production is no longer a forecast. It is a fact of global industrial life. In 2025, Chinese manufacturers controlled around 70 percent of the global EV battery market, a sharp increase from less than 50 percent in 2021. The country’s battery cell production accounted for more than 80 percent of global output, with battery pack prices in China running about 30 percent lower than in North America and 35 percent lower than in Europe. China sold16. 49 million new energy vehicles in 2025, up28. 2% year on year, while NEV production reached16. 626 million units, keeping China in the global lead for the 11th straight year. For global executives, the issue is no longer simple sourcing. TheChina EV batterystory now sits at the center of global mobility strategy because battery decisions influence cost, charging experience, compliance exposure, and overseas competitiveness. Why China’s EV Battery Market Matters NowAlt text: electric car battery inside a vehicle’s engine compartmentIn 2025,China’s new energy vehiclesales stayed far ahead of other markets. The International Energy Agency estimates that China accounted forsix out of every ten electric cars sold globally in 2025, while Chinese automakers supplied60% of global electric car sales. That demand gave battery firms a massive domestic testing ground. It also pushedEV battery companiesto accelerate efforts in cost reduction, pack design, charging speed, safety, and chemistry diversification. This is why China is shaping global battery standards from the market upward. Buyers in Europe, Southeast Asia, Latin America, and the Middle East are not only importing Chinese electric vehicles. They are bringing the battery logic in-house, from LFP affordability to integrated packs and lifecycle tracking. In 2025, China produced nearly75% of the world’s electric cars, and Chinese electric car exports doubled to more than2. 5 million vehicles, according to the IEA. For global business leaders,China’s electric-vehicle battery development should be viewed as a signalingsystem. It shows where price pressure is moving, which chemistries are scaling, and how fast local supply chains can turn new battery formats into commercial products. LFP Has Become China’s Mass Market EngineThe most significant chemical story in China’s EV battery sector is the near-total victory of lithium iron phosphate (LFP) chemistry over nickel-based alternatives. In 2025, LFP batteries accounted for 81. 2 percent of domestic power battery installations, with 625. 3 GWh installed, compared with 144. 1 GWh for ternary NMC batteries. The gap widened dramatically from the previous year, with LFP installations growing 52. 9 percent while ternary grew just 3. 7 percent. This shift reflects both cost pressures and technical progress. LFP batteries have historically traded energy density for safety and cost. Chinese electric vehicle batterymanufacturers have narrowed that density gap through advances in high-voltage LFP chemistries and cell-to-pack architectures. The result is an LFP product that meets the range requirements of mainstream passenger EVs while undercutting ternary on price. The dominance is not limited to China. LFP batteries, pioneered by Chinese firms BYD and CATL, now account for more than half of global electric vehicle demand. More than 98 percent of LFP cathode material and LFP battery cells are produced in China. This concentration gives Chinese EV battery makers structural cost advantages that foreign competitors cannot easily replicate. Ternary Batteries Still Matter For Premium SegmentsTernary batteries continue to play a role in premium long-range vehicles, but their domestic market share has contracted to 18. 7 percent. The trend line points toward further erosion as LFP energy density continues to improve. For electric vehicle battery companies operating outside China, the LFP challenge is existential: competing on cost against a supply chain that controls 98 percent of the material base is not a sustainable strategy. Scale: Production Volumes and Market ConcentrationChina’s EV battery manufacturing capacity in 2025 reached staggering dimensions. Domestic power battery installations totaled 769. 7 GWh, up 40. 4 percent year on year. Total production across power and other battery categories reached 1,468. 8 GWh in the first 11 months of 2025, a 51. 1 percent increase. Global installations reached 1,187 GWh in 2025, up 31. 7 percent from 2024. Chinese companies captured the vast majority of this growth. Six of the top ten global EV battery suppliers are Chinese, with a combined market share of 70. 4 percent. The top six suppliers globally control 78. 3 percent of the market, reflecting extreme concentration that favors scale players. CATL Shows The Power Of Platform LeadershipCATL remains the undisputed leader. The company reported 2025 revenue of RMB 423. 7 billion, up 17 percent, and net profit of RMB 72. 2 billion, up 42 percent. The company also maintained a39. 2% global power battery market sharein 2025, according to SNE Research data cited by CATL. Global power battery installations reached 464. 7 GWh, giving CATL a 39. 2 percent market share, up 1. 2 percentage points from 2024. The company held the top position for the ninth consecutive year. CATL’s domestic installations totaled 333. 57 GWh, representing a 43. 42 percent share, down 1. 67 percentage points from 2024. BYD Connects Batteries, Vehicles, And ChargingBYD’s battery position is different because it is vertically integratedthrough vehicles, batteries, chips, and charging architecture. Its 2025 Super e-Platform showed how battery design is being linked to ultra-fast charging, high-voltage systems, motors, and silicon carbide power electronics. BYD says the Super e-Platform uses a full-domain1000Vhigh-voltage architecture, supports1 megawattcharging power, and can add400 km of range in five minutesunder its stated conditions. This matters because theEV Batteryis increasingly judged by the total user experience. For BYD, battery capabilities support both product storytelling and infrastructure strategy. For other brands, this raises the bar. Battery sourcing without system integration may leave performance value on the table. CALB (China Aviation Lithium Battery) ranked third globally with 62. 8 GWh of installed capacity, up 52. 6 percent. Gotion High-tech delivered the fastest growth among top-ten players, with installations rising 82. 5 percent to 53. 5 GWh. Eve Energy and Sunwoda grew at 67. 5 percent and 64. 1 percent, respectively. New entrants are also emerging. Jiyo Tongxing, formed in April 2025 through the consolidation of Geely’s battery operations, entered the top fifteen domestic rankings for the first time. Yinpai Battery, incubated by GAC Aion, also joined the top tier. This diversification reduces the concentration risk that has long characterized China’s EVbattery supply chain. The EV Battery Supply Chain Is Becoming More StrategicChina’s EV battery supply chain is vertically integrated to a degree unmatched by any other country. The chain spans raw material extraction, refining, electrode production, cell assembly, pack integration, and end-of-life recycling. Each layer reinforces the others, creating cost and speed advantages that foreign competitors cannot easily neutralize. Raw Materials and Processed InputsChina controls a dominant share of the processing capacity for key battery minerals. The country refines roughly 60 percent of the world’s lithium and produces more than 80 percent of the world’s graphite anode material. Graphite deployment in Chinese EVs and exports totaled 406. 8 kilotonnes from January through August 2025, accounting for 67 percent of the global total. This control extends to cathode materials. LFP cathode production is almost entirely concentrated in China. The country also dominates production of artificial graphite anodes, which are critical to high-performance EV battery cells. Export Controls as Strategic LeverageIn 2025, China converted its supply chain dominance into explicit policy leverage. On October 9, the Ministry of Commerce and the General Administration of Customs issued Announcement No. 58, imposing export controls on lithium-ion batteries, artificial graphite anode materials, and related production equipment and technology, effective November 8, 2025. The controls cover batteries with an energy density of 300 Wh/kg or above, cathode materials including LFP, and graphite anode production technology. These measures followed earlier restrictions on LFP battery production technology imposed in July 2025. The controls were suspended effective November 7, 2025, until November 10, 2026, but the signal was clear: China views its EV battery technology and material base as strategic assets subject to state control. For global automakers and EV battery technology companies, these controls introduce new supply risk. Access to advanced Chinese battery technology and materials now requires navigating a licensing regime. The suspension provides temporary relief but does not eliminate the underlying policy direction. What Global Business Leaders Should Watch NextThe first issue is how long LFP price pressure can continue without damaging upstream profitability. The second is how fast sodium ions can find durable use cases beyond early product launches. The third is how global rules will affect Chinese battery exports, local assembly, and licensing models. The fourth is how recycling changes material access. The fifth is how deeply batteries become integrated with software, charging networks, and vehicle platforms. For global automakers, suppliers, investors, and technology leaders, China is no longer a market to observe from the outside. It is the operating center of battery competition. The companies that understand China’s battery chemistry, scale logic, and supply chain structure will make better decisions on partnerships, procurement, product design, and market entry. TheEV Batterysector in China is now a strategic lens for reading the future of electric mobility. It tells us which cost curves are real, which technologies are deployable, and which companies can translate industrial-scale operations into global influence. Understand China’s EV Battery Advantage With ChoZanChina’sEV Batteryecosystem is moving fast, and the real advantage is not just in cells or chemistry. It sits across suppliers, manufacturing clusters, charging systems, recycling rules, and companies like CATL and BYD, turning innovation into scale. ChoZanhelps global leaders make sense of this landscape through China-focused research, expert briefings, strategy workshops, and tailoredinnovation tours. For teams working in EVs, batteries, mobility, energy, or investment, ChoZan can help benchmark ChineseEV battery companies, assess supply chain risks, and translate market signals into practical decisions. Whether your team is exploring sourcing, partnerships, market entry, or competitor strategy, ChoZan provides the context you need to move with confidence. Book a consultationwith ChoZanto design the right research project or leadership learning program. FAQsWhat Is The Best Chemistry For An EV Battery In China?The bestEV Batterychemistry depends on vehicle use. LFP often fits affordable passenger cars and fleets because it balances cost, safety, and cycle life. Ternary chemistry works better for premium models that need higher energy density. Why Are Chinese ev battery companies So Competitive?Chineseev battery companiesare competitive because they operate near automakers, materials suppliers, equipment makers, and recycling networks. This creates faster testing cycles, lower coordination costs, and stronger production learning than markets with thinner industrial clusters. How Should Automakers Choose electric vehicle battery manufacturers In China?Automakers should assesselectric vehicle battery manufacturersthrough chemistry roadmap, quality record, plant utilization, overseas compliance, warranty support, and integration capability. A low cell price alone does not reveal launch risk or long term supplier strength. What Makes The ev battery supply chain In China Different?Theev battery supply chainin China is different because many critical suppliers are close to each other. Materials, cells, packs, testing, equipment, and vehicle programs interact quickly, which supports fast product iteration and cost control. Are Chinese ev battery makers Moving Overseas?Yes, manyev battery makersare expanding overseas through factories, joint ventures, licensing, and local partnerships. The goal is to serve regional automakers, reduce tariff exposure, and meet local content rules in key growth markets. What Do ev battery technology companies Focus On Now?Manyev battery technology companiesnow focus on fast charging, thermal safety, sodium ion, solid state research, battery management software, pack integration, and recycling. The strongest firms connect chemistry progress with real vehicle performance and production readiness. Is A china ev battery Supplier Suitable For Premium Cars?Achina ev batterysupplier can be suitable for premium cars if it offers high energy density, fast charging support, strong safety validation, and stable global service. Premium programs need deeper technical integration than basic cell procurement. How Does Recycling Affect china electric vehicle battery Strategy?Recycling affectschina electric vehicle batterystrategy by improving access to lithium, nickel, cobalt, and other materials. It also supports compliance, lowers waste risk, and gives large battery firms more control over future material loops. What Should Investors Watch In electric vehicle battery companies?Investors should watch margins, customer concentration, chemistry mix, overseas revenue, capacity use, R&D spending, and recycling access inelectric vehicle battery companies. Announced capacity matters less than profitable utilization and durable customer demand. Why Does ev battery manufacturing Matter For EV Brands?ev battery manufacturingmatters because it affects cost, safety, range, charging speed, and warranty exposure. EV brands that understand manufacturing constraints can design better platforms and avoid claims that their supply base cannot support.