Wealth Taxes in Europe, 2026
Wealth taxes not only collect little revenue and create legal uncertainty, but an OECD report argues that they can also disincentivize entrepreneurship, harming innovation and long-term growth.
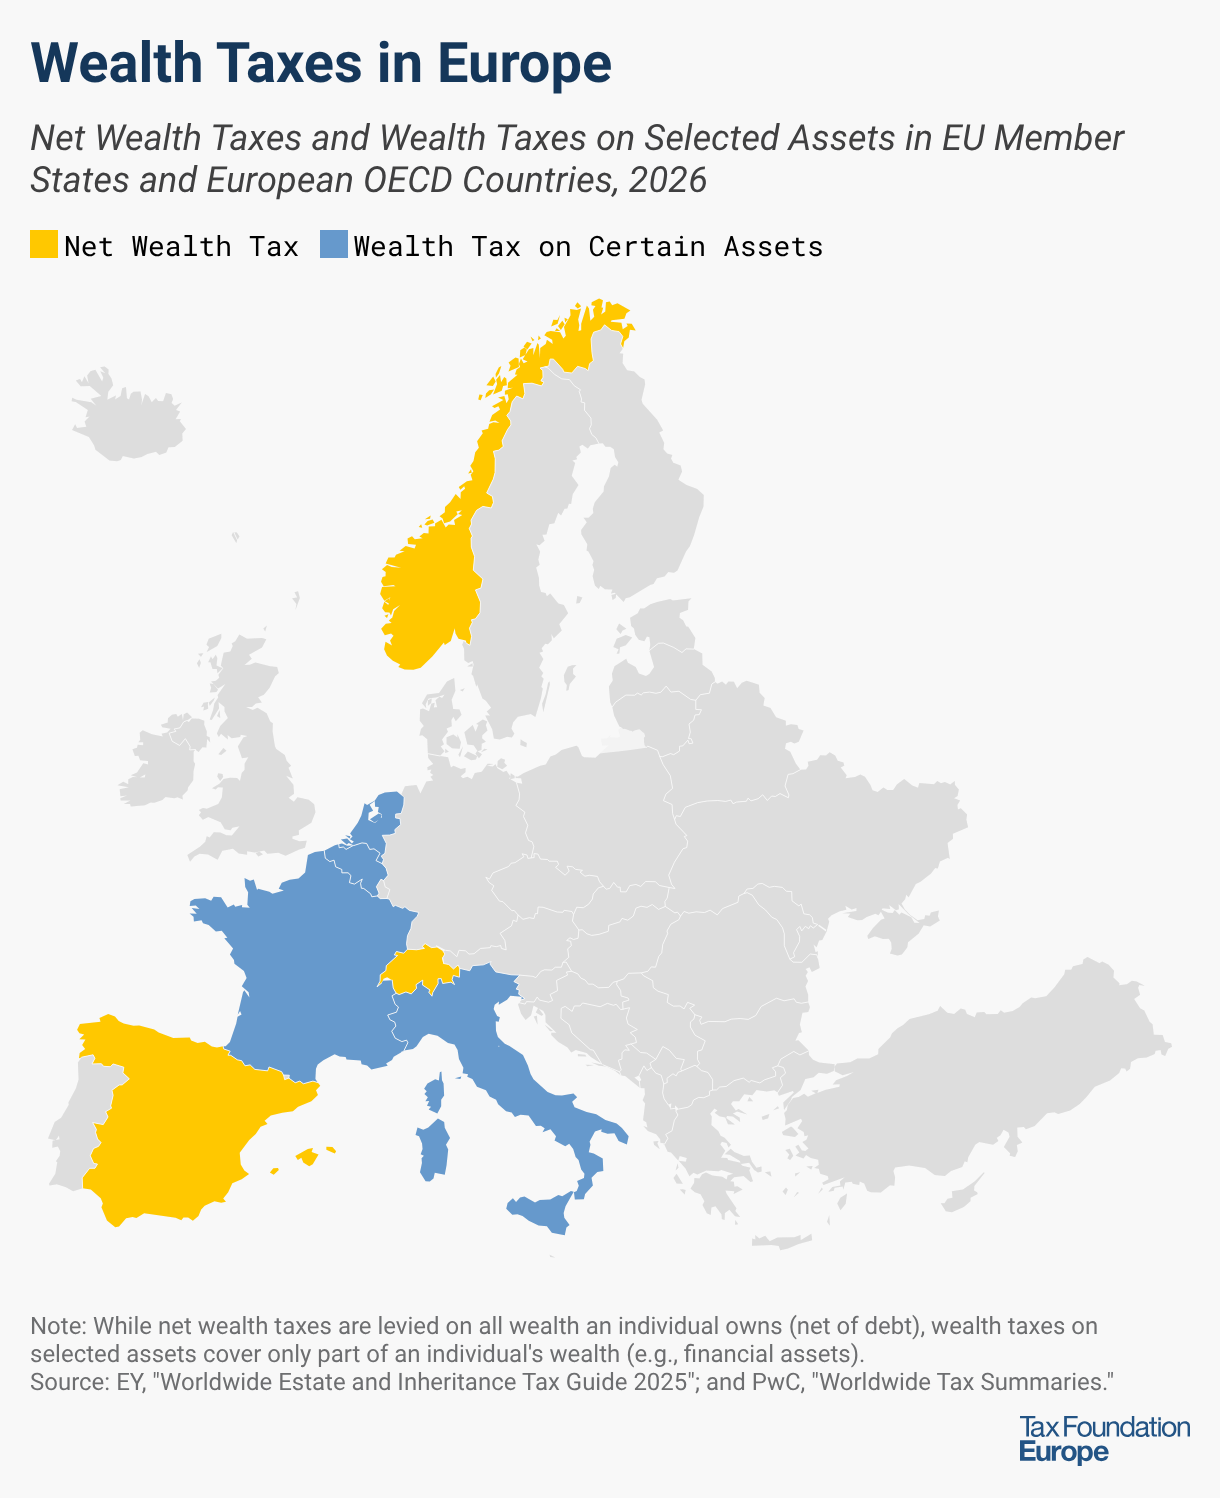
Net wealth taxes are recurrent taxes on an individual’s wealth, net of debt. The concept of a netwealth taxA wealth tax is imposed on an individual’s net wealth, or the market value of their total owned assets minus liabilities. A wealth tax can be narrowly or widely defined, and depending on the definition of wealth, the base for a wealth tax can vary. is similar to a realproperty taxA property tax is primarily levied on immovable property like land and buildings, as well as on tangible personal property that is movable, like vehicles and equipment. Property taxes are the single largest source of state and local revenue in the U. S. and help fund schools, roads, police, and other services. . But instead of only taxing real estate, it covers all wealth an individual owns. As today’s map shows, only three European countries coveredlevya net wealth tax—Norway,Spain,andSwitzerland. France,Italy,Belgium,andthe Netherlandslevy wealth taxes on selected assets but not on an individual’s net wealth per se. Net Wealth Taxes in EuropeNorwaylevies a net wealth tax of 1 percent on individuals’ wealth stocks exceeding NOK 1. 9 million (EUR 172,710 or USD 198,996), with 0. 35 percent going to municipalities and 0. 65 percent to the central government. Norway’s net wealth tax dates to 1892. Additionally, for net wealth exceeding NOK 21. 5 million (USD 2. 2 million), thetaxA tax is a mandatory payment or charge collected by local, state, and national governments from individuals or businesses to cover the costs of general government services, goods, and activities. rate is 1. 1 percent. Spain’snet wealth tax is aprogressive taxA progressive tax is one where the average tax burden increases with income. High-income families pay a disproportionate share of the tax burden, while low- and middle-income taxpayers shoulder a relatively small tax burden. ranging from 0. 16 percent (in Navarra) to 3. 5 percent on wealth stocks above EUR 700,000 (USD 805,330; lower in some regions), with rates varying substantially across Spain’s autonomous regions. Andalusia, Cantabria, La Rioja, Madrid, and Murcia offer 100 percent relief to individuals with net wealth below €3 million. Extremadura offers 100 percent relief. Spanish residents are subject to the tax on a worldwide basis while nonresidents pay the tax only on assets located in Spain. Additionally, the Spanish central governmentintroduceda “solidarity wealth tax” in 2022 ranging from 1. 7 percent to 3. 5 percent on individuals with net assets exceeding EUR 3 million (USD 3. 46 million). Under this tax scheme, the central government collects any additional revenue from the solidarity tax once the regional wealth tax collection is deducted. In December 2023, the Spanish central government extended the solidarity tax’s application indefinitely. Consequently, Madrid and Andalusia restored the wealth tax so that the regional governments retain the revenues the central government planned to collect. Switzerlandlevies its net wealth tax at the cantonal level and covers worldwide assets (except real estate and permanent establishments located abroad). The tax rates and allowances vary significantly across cantons. The Swiss net wealth tax was first implemented in 1840. Wealth Taxes on Selected AssetsFranceabolished its net wealth tax in 2018 and replaced it that year with a real estate wealth tax. French tax residents whose net worldwide real estate assets are valued at or above EUR 1. 3 million (USD 1. 5 million) are subject to the tax, as well as non-French tax residents whose net real estate assets located in France are valued at or above EUR 1. 3 million. Depending on the net value of the real estate assets, the tax rate ranges as much as 1. 5 percent. Italytaxes financial assets held abroad without Italian intermediaries by individual resident taxpayers at 0. 2 percent and 0. 4 percent for assets held in certain countries. Since 2023, a tax of 0. 2 percent per year has also applied to crypto assets held with a nonresident intermediary or stored on a USB stick or smartphone. In addition, real estate properties held abroad by Italian tax residents are taxed at 1. 06 percent. Since 2021, Belgiumhas had a solidarity tax or tax on securities accounts (TSA) of 0. 15 percent on securities accounts with an average value of EUR 1 million (USD 1. 15 million). In theNetherlands, the value of net wealth, excluding primary residence and substantial interests in companies, is included in the income tax. Nevertheless, the Dutch Supreme Court ruled in 2021 that this system violates European law regarding property rights and non-discrimination. In 2022, a new temporary alternative system for the years 2023, 2024, 2025, 2026, and 2027 was proposed where each asset category (e. g. , savings, debts, and others) would have its own deemed return. For 2026, the weighted average yield over all categories will be applied to the total assets above a personal exemption of EUR 59,357 (USD 68,373) to determine the taxable benefit that will be subject to tax at a flat rate of 36 percent. The government is aiming to have anew systembased on actual returns by2028. Wealth taxes not only collectlittle revenueand create legal uncertainty, but anOECD reportargues that they can also disincentivize entrepreneurship, harming innovation andlong-term growth. Instead of reforming and hiking the wealth tax,one of the most harmful taxesever created, countries should repeal it. Stay informed on the tax policies impacting you. Subscribe to our free newsletter to get the latest tax data, news and analysis. Subscribe