The widening Middle East war is threatening your mortgage rate again
Skip to ContentNewsArchivesEconomyEnergyOil & GasRenewablesElectric VehiclesMiningCommoditiesAgricultureReal EstateMortgagesMortgage RatesFinanceBankingInsuranceFintechCryptocurrencyWorkWealthSmart. . .
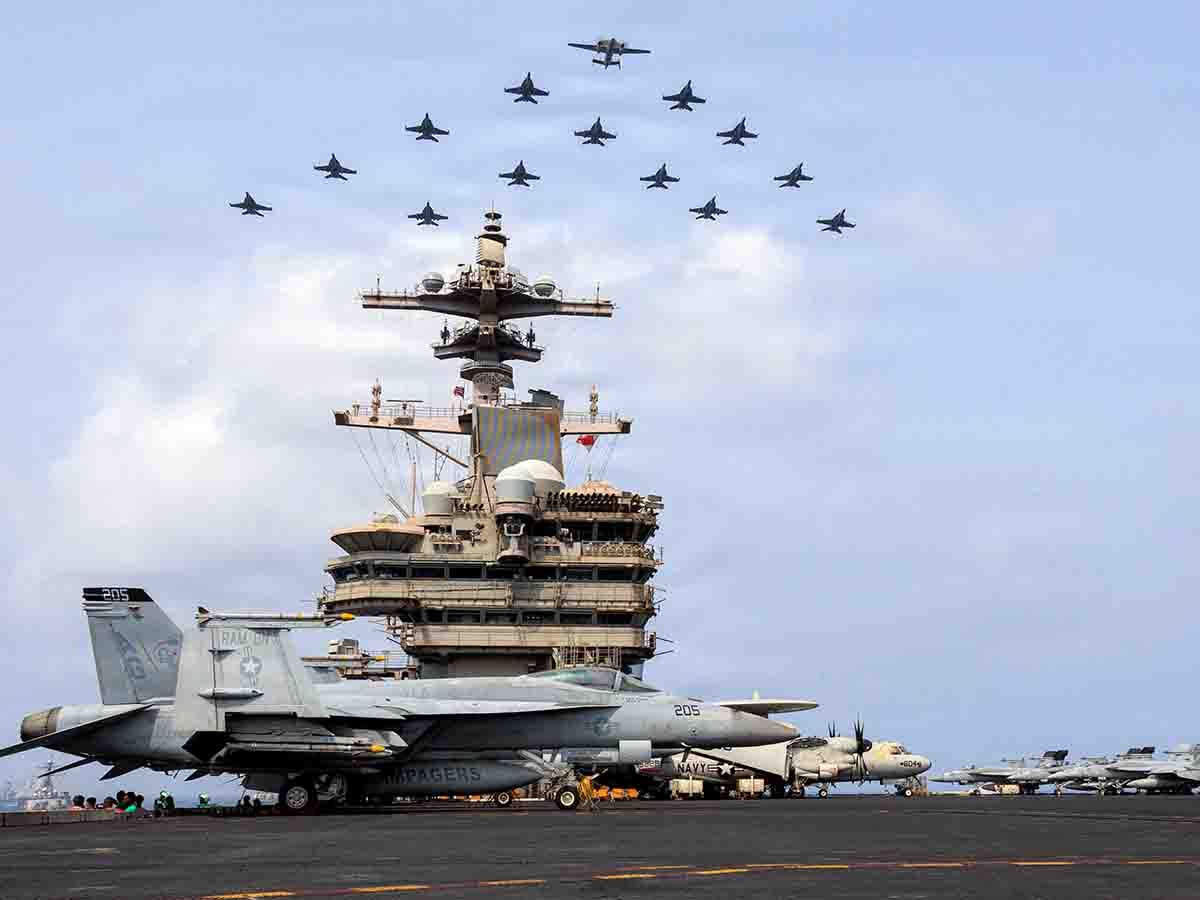
Skip to ContentNewsArchivesEconomyEnergyOil & GasRenewablesElectric VehiclesMiningCommoditiesAgricultureReal EstateMortgagesMortgage RatesFinanceBankingInsuranceFintechCryptocurrencyWorkWealthSmart MoneyWealth ManagementInvestorPersonal FinanceFamily FinanceRetirementTaxesHigh Net WorthFP CommentExecutive WomenPuzzmoNewslettersFinancial TimesBusiness EssentialsMoreInnovationInformation TechnologyFP500PodcastsSmall BusinessLives ToldTails ToldShoppingFinancial Post StoreObituariesPlace a NoticeAdvertisingAdvertising With UsAdvertising SolutionsPostmedia Ad ManagerSponsorship RequestsClassifiedsPlace a Classifieds adWorkingProfileSettingsMy SubscriptionsSaved ArticlesMy OffersNewslettersCustomer ServiceFAQNewsEconomyEnergyMiningReal EstateFinanceWorkWealthInvestorFP CommentExecutive WomenPuzzmoNewslettersFinancial TimesBusiness EssentialsHomeReal EstateMortgagesThe widening Middle East war is threatening your mortgage rate againRobert McLister: New round of fighting has oil prices and bond yields climbing again. Plus: Why the CMHC doesn't plan to raise default insurance fees anytime soonYou can save this article by registering for freehere. Orsign-inif you have an account. This U. S. Navy handout photo released on July 15, 2026, and taken on June 30 by US Central Command Public Affairs shows the Carrier Air Wing 7 flying in formation over the USS George H. W. Bush in the Arabian Sea. The U. S. launched a wave of strikes against Iran on July 15 in a return to war between the two foes. Bond yields, which determine mortgage rates, are rising as a consequence. Photo by US NAVY / NAVCENT PUBLIC AFFAIRS/AFPThis week brings a grab bag of mortgage updates, featuring musings fromCanada Mortgage and Housing Corp. CEO Coleen Volk, Realtor. ca CEO Scott Neil, and concerning new developments in the mortgage rate market. Subscribe now to read the latest news in your city and across Canada. Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman, and others. Daily content from Financial Times, the world's leading global business publication. Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account. National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on. Daily puzzles, including the New York Times Crossword. Subscribe now to read the latest news in your city and across Canada. Exclusive articles from Barbara Shecter, Joe O'Connor, Gabriel Friedman and others. Daily content from Financial Times, the world's leading global business publication. Unlimited online access to read articles from Financial Post, National Post and 15 news sites across Canada with one account. National Post ePaper, an electronic replica of the print edition to view on any device, share and comment on. Daily puzzles, including the New York Times Crossword. Create an account or sign in to continue with your reading experience. Access articles from across Canada with one account. Share your thoughts and join the conversation in the comments. Enjoy additional articles per month. Get email updates from your favourite authors. Create an account or sign in to continue with your reading experience. Access articles from across Canada with one accountShare your thoughts and join the conversation in the commentsEnjoy additional articles per monthGet email updates from your favourite authorsSign In or Create an AccountorLet’s start with the latest threats to mortgage pricing. Oil priceshave staged quite the comeback. On Thursday, Brent crude futures roared past US$100 a barrel, as the United States struckIranand Iran hit back across the Gulf, targeting Kuwait and Jordan. Yemen’s Houthis joined in, striking two Saudi oil tankers in the Red Sea and blockading Bab al-Mandeb,giving oil a second major shipping chokepoint to go with theStrait of Hormuz,because one apparently wasn’t stressful enough. SUBSCRIBER EXCLUSIVE: FP West: Energy Insider brings you behind the oilpatch’s closed doors with exclusive insights from insiders every Wednesday morning. By signing up you consent to receive the above newsletter from Postmedia Network Inc. A welcome email is on its way. If you don't see it, please check your junk folder. The next issue of FP West: Energy Insider will soon be in your inbox. We encountered an issue signing you up. Please try againThe potential mortgage fallout is unambiguous. Global bond yieldsare hitting or nearing multi-year highs on fears inflation could reaccelerate. And oil isn’t the only thing menacingmortgage rates. Donald Trump‘s newesttariffsare a second threat. The president has taken advantage of Canada’s weak response to U. S. trade aggression by slapping another 50 per cent penalty on $28 billion of Canadian exports to the U. S. Some Canadian leaders are growing impatient with what they view asPrime Minister Carney’s passive and concessionary response, which critics say surrenders leverage, relies endlessly on unproductive, ongoing trade talks and delays the inevitable. Assuming Trump’s tariffs are not just a negotiating ploy and take effect on Aug. 19 as announced, we can’t rule out Canada retaliating with more inflation-triggering tariffs of its own. All of this comes as the North American economy gathers steam, thanks partly to AI investment. That could pour more fuel on inflation, assuming Trump doesn’t kneecap growth by following through on new tariffs. Given all these risks, anyone shopping for a fixed-rate mortgage in the next four months should lock in a rate immediately, if not sooner. In aninterview with MortgageLogic. newslast week, CMHC CEO Coleen Volk said that mortgage default insurance fees are staying put, despite rising arrears. “There hasn’t been anything that would cause us a real rethink on that,” she said, adding that the CMHC is the price leader on default premiums and they’re set for “the long term. ”On the government’s low-risk (and profitable) mortgage securitization program, which small and mid-size lenders rely on to compete with big banks, she admitted that, “We do have more demand than we are able to accommodate. ”Volk acknowledged that there may be segments of the mortgage market with insufficient competition. Refinances are an obvious one to anyone in the mortgage business, given Big Six banks have a dominant cost advantage on non-default-insured mortgages due to their leading funding costs. Volk didn’t want to comment on whether she supported a reintroduction of insured refinances, the one fix that would actually solve Canada’s competition problem with uninsured mortgages. Insured refis “would be a decision of the Department of Finance,” she said. “Generally in life, it’s a good idea for me to not cross-thread myself with the Department of Finance. ”She added that insured single-family refinances are currently available for the construction of secondary suites. “Perhaps the Department of Finance would consider extending that,” she said. Volk also declined to support raising the home value limit on “low-ratio” insured mortgages (i. e. , those with 20 per cent equity or more) from $1 million to $1. 5 million. Doing so would significantly improve mortgage competition in that segment, critical in high-priced markets like Toronto and Vancouver. The reason being: securitized insured mortgages allow for significantly lower interest rates than uninsured mortgages. CMHC already insures mortgages on properties up to $1. 5 million for people with much less skin in the game, a mere 7. 5 to 8. 3 per cent down in those cases. And those properties have higher default rates than low-ratio mortgages. Consequently, purchasers and mortgage renewers with $1 to $1. 5 million homes and big down payments are left paying higher rates — for seemingly no other reason than the Department of Finance’s refusal to correct this problem. Realtor. ca CEO Scott Neil told me in a recentinterviewthat his website’s market share of real estate shoppers rose by five percentage points in 2025, to 61 per cent. He credits slicker search tools for the gain and promises more artificial intelligence features to make home searching easier in the future. AI, he acknowledged, can let house hunters type plain-language requests such as, “Find me houses with a sunset view and a backyard that faces west. ” But he wasn’t confident that the website’simplementation of AI will actually be that user-friendly. One thing it has going for it, however, is restrictive data access. “We likely have the most complete listing data in the market,” Neil said. Canada has no aggregators that sell nationwide MLS data, so tech-savvy innovative competitors find it near-impossible to compete withRealtor. cacoast-to-coast. By comparison, in the U. S. , antitrust pressure has partly pried that door open, bringing more innovation to real estate search and analysis. In any case, the portal’s dominant position lets it reinvest in itself, Neil said. As for AI disintermediating real estate agents, Neil said, “There’s massive value in a realtor guiding you through that process, asking you the right questions, making sure that you’re thinking of everything…. I just don’t think AI can do (that) at this point in time. ”He also does not envision a time where customers will be able to list their homes themselves onRealtor. ca, due to the “complexity” of the process. On mortgages, Neil acknowledgedRBC’s privileged positiononhis website, which lets folks who see real estate listings click a link to the bank to get mortgage info. “I believe there’s a great opportunity to provide more choice” for mortgage consumers, he adds. “And that’s something that we will likely pursue. ”There’s no telling, however, ifRealtor. cawill ever have a true open marketplace of lenders and mortgage brokers on the site. Home shoppers would surely value that for comparison shopping, as opposed to being steered toward the handful of partners paying for the privilege of meeting them. Robert McListeris a mortgage strategist, interest rate analyst and editor ofMortgageLogic. news. You can follow him on X at@RobMcLister. For the best national insured and uninsured mortgage rates, updated daily, please visit our mortgage rate pagehere. Join the ConversationThis website uses cookies to personalize your content (including ads), and allows us to analyze our traffic. Read more aboutcookies here. By continuing to use our site, you agree to ourTerms of UseandPrivacy Policy.